In Brief
- Quarterly income tax in the Philippines is cumulative, not per-quarter. Each filing covers the year-to-date income, then subtracts what was already paid.
- Self-employed individuals have three options: the 8% flat rate, graduated rates with the Optional Standard Deduction (40%), or graduated rates with itemized deductions.
- The 8% flat rate is available only to non-VAT-registered individuals with gross sales not exceeding ₱3,000,000. Above that, the taxpayer is disqualified and liable for VAT.
- Non-VAT filers on graduated rates also pay a 3% percentage tax on gross sales, filed separately using BIR Form 2551Q.
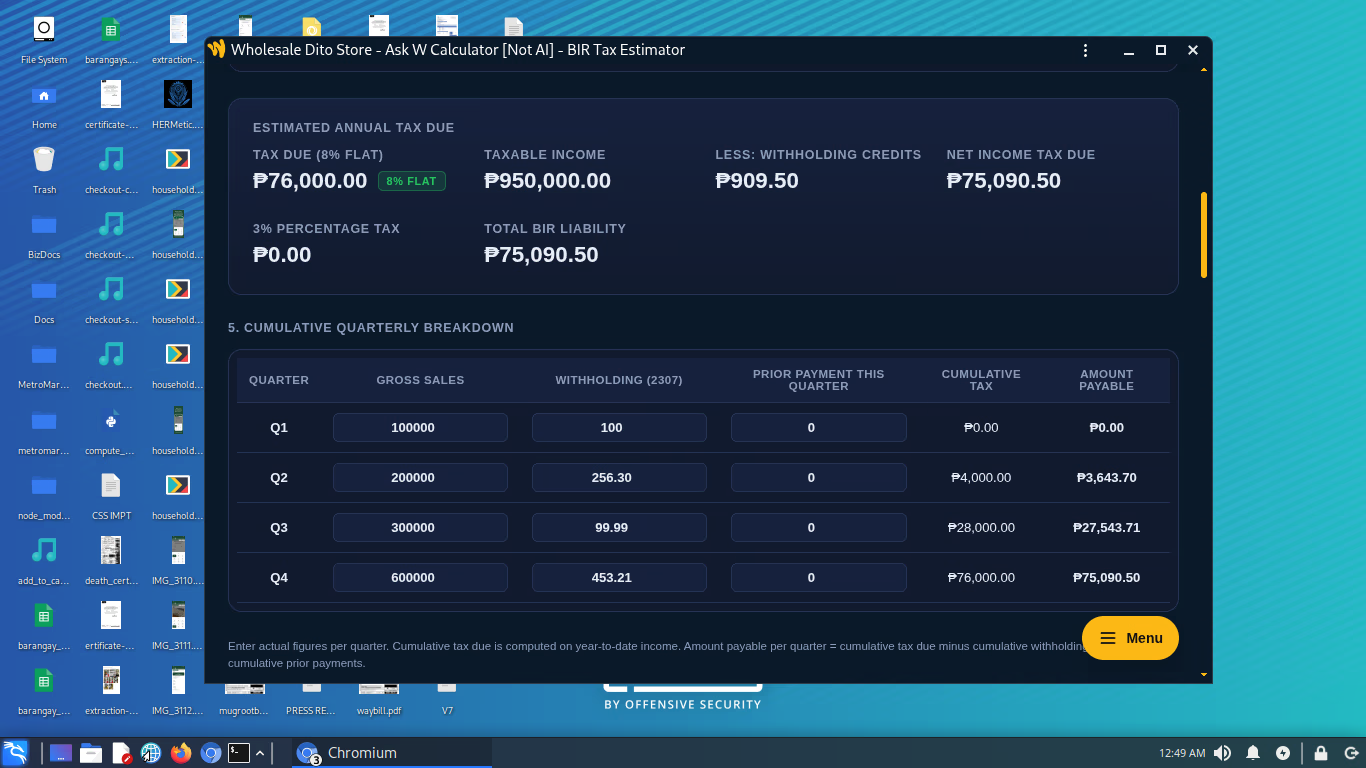
- This article explains the cumulative rule and the three options. The Ask W Calculator [Not AI] - BIR Tax Estimator computes them.
Direct Answer
Quarterly income tax in the Philippines is cumulative. Q1 covers January to March. Q2 covers January to June. Q3 covers January to September. Each filing computes the tax on year-to-date income, then subtracts the tax already paid in prior quarters. The difference is the amount payable for that quarter.
For a self-employed individual with a gross of ₱400,000 in Q1 and ₱500,000 in Q2, the Q1 filing uses ₱400,000. The Q2 filing uses ₱900,000, not ₱500,000. That is the rule most filers get wrong.
Who This Guide Is For
This guide is for self-employed individuals and professionals in the Philippines. Freelancers, consultants, sole proprietors, and practitioners who file BIR Form 1701Q.
It is not for:
- Salaried employees whose employer withholds tax. They file BIR Form 1700 or 1701A.
- Mixed-income earners with both salary and business income. The rules differ because the ₱250,000 exemption is consumed by compensation.
- Corporations. They file BIR Form 1702Q and follow different rules.
The Three Tax Options for Self-Employed Individuals
A self-employed individual chooses one of three options at the start of the taxable year. The choice is generally irrevocable for the year.
Option 1: The 8% Flat Rate
Tax is 8% of gross sales or receipts in excess of ₱250,000. The ₱250,000 is a deduction, not a bracket.
Example: gross of ₱1,000,000. Taxable amount is ₱750,000. Tax is 8% of ₱750,000, or ₱60,000.
Eligibility: Must be non-VAT-registered. Gross sales must not exceed ₱3,000,000. The 8% is in lieu of both graduated income tax and the 3% percentage tax.
Option 2: Graduated Rates with OSD
The Optional Standard Deduction is 40% of gross sales. Taxable income is 60% of gross. Graduated rates then apply.
Example: gross of ₱1,000,000. OSD is ₱400,000. Taxable income is ₱600,000. Tax is ₱22,500 plus 20% of the excess over ₱400,000. That is ₱22,500 plus ₱40,000, or ₱62,500.
Percentage tax of 3% of gross also applies. For ₱1,000,000, that is ₱30,000.
Option 3: Graduated Rates with Itemized Deductions
The taxpayer deducts actual business expenses. These must be ordinary, necessary, and substantiated. The graduated rates then apply to the resulting taxable income.
Example: gross of ₱1,000,000, deductions of ₱400,000. Taxable income is ₱600,000. Tax is the same as Option 2: ₱62,500. Percentage tax of 3% also applies.
The Cumulative Rule: How Quarterly Filing Actually Works
This is the mechanic most self-employed filers misunderstand. Quarterly income tax in the Philippines is not computed per quarter. It is computed on the year-to-date total.
The formula for each quarter is:
Worked Example: 8% Flat Rate
A freelancer elects the 8% rate. Quarterly gross receipts are:
- Q1: ₱300,000
- Q2: ₱400,000
- Q3: ₱300,000
- Q4: ₱200,000
- Annual gross: ₱1,200,000
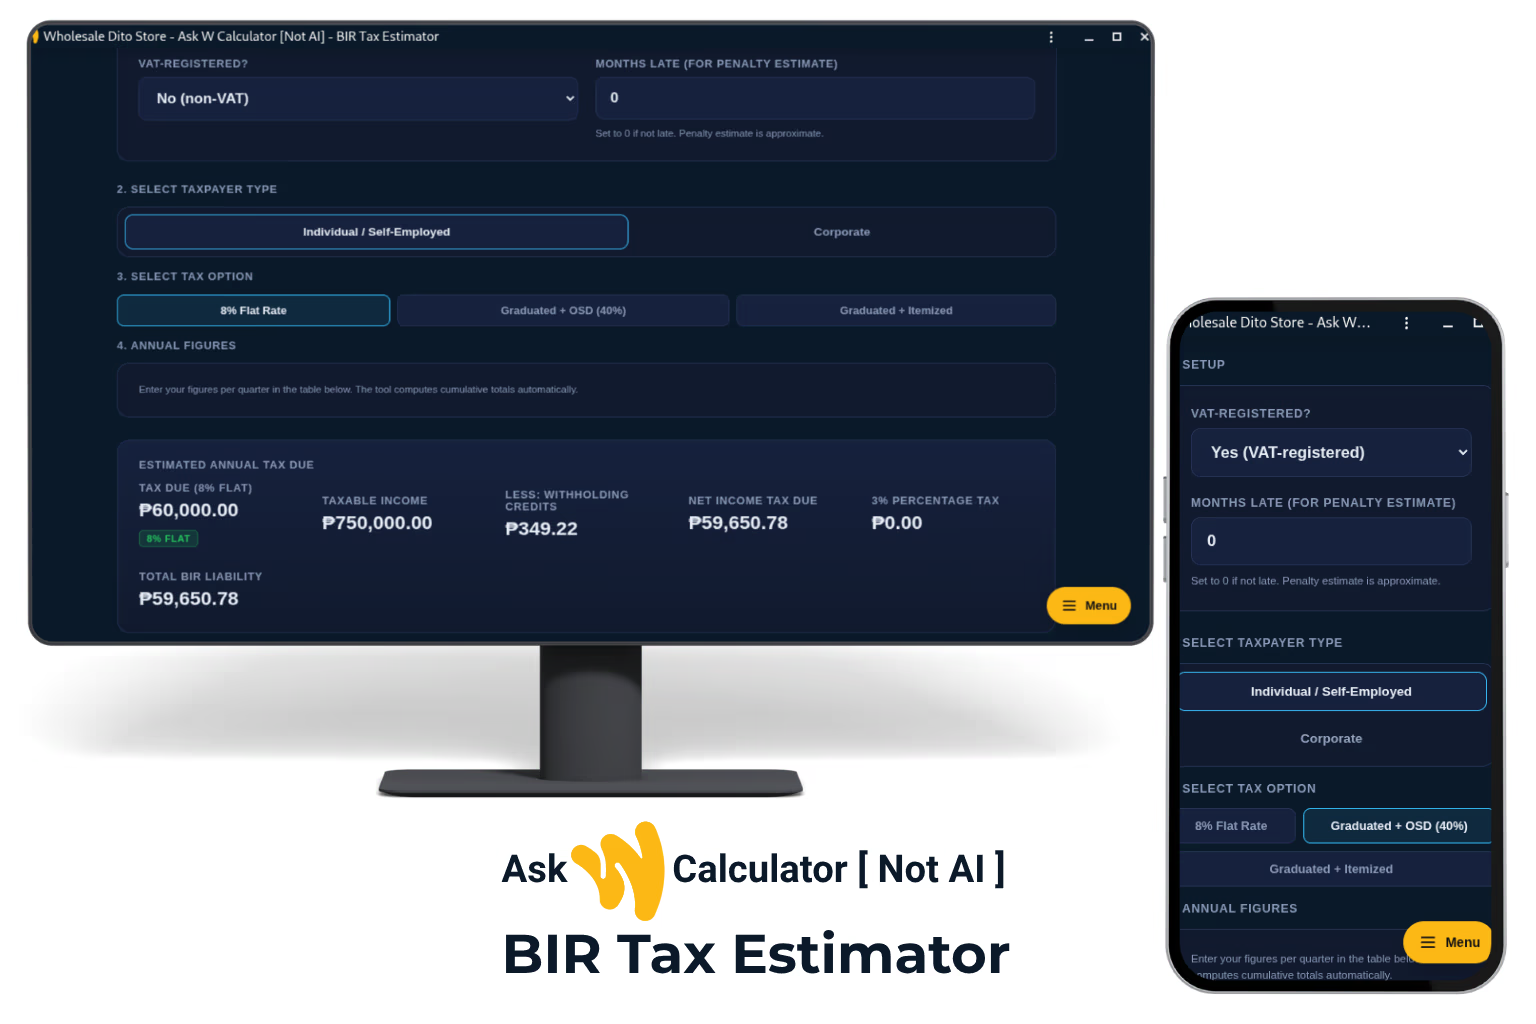
Q1 filing (covers January to March):
- Year-to-date gross: ₱300,000
- Excess over ₱250,000: ₱50,000
- Tax: 8% of ₱50,000 = ₱4,000
- Prior payments: ₱0
- Amount payable: ₱4,000
Q2 filing (covers January to June):
- Year-to-date gross: ₱700,000
- Excess over ₱250,000: ₱450,000
- Tax: 8% of ₱450,000 = ₱36,000
- Prior payments: ₱4,000
- Amount payable: ₱32,000
Q3 filing (covers January to September):
- Year-to-date gross: ₱1,000,000
- Excess over ₱250,000: ₱750,000
- Tax: 8% of ₱750,000 = ₱60,000
- Prior payments: ₱36,000
- Amount payable: ₱24,000
Q4 / Annual filing (covers January to December):
- Year-to-date gross: ₱1,200,000
- Excess over ₱250,000: ₱950,000
- Tax: 8% of ₱950,000 = ₱76,000
- Prior payments: ₱60,000
- Amount payable: ₱16,000
The four payments total ₱76,000, which is exactly the annual tax. Nothing is double-counted, and nothing is missed.
If the filer had computed each quarter in isolation, the Q2 tax would have been 8% of ₱150,000 (₱400,000 minus ₱250,000), or ₱12,000. That would have been wrong. The correct Q2 payment is ₱32,000, because the ₱250,000 deduction applies once per year, not once per quarter.
The ₱3,000,000 Cap and What Happens When You Cross It
The 8% flat rate is available only to non-VAT-registered individuals with gross sales not exceeding ₱3,000,000. The cap is not a soft guideline. Crossing it has three consequences.
- Disqualification from the 8% rate. The taxpayer must switch to graduated rates for the entire taxable year.
- Mandatory VAT registration. Once gross sales exceed the threshold, the taxpayer must register for VAT within the prescribed period.
- Retroactive recalculation. The graduated rates apply from the start of the year, and the taxpayer must recompute prior quarters and settle the difference.
The cap applies to the annual gross. If a filer reaches ₱3,000,000 in Q3 but expects to stay under ₱3,000,000 for the full year, the cap is not breached because the annual figure is what matters. This is why the threshold must be monitored cumulatively, not per-quarter.
The 3% Percentage Tax: A Separate Liability
Non-VAT-registered individuals who choose graduated rates also pay a 3% percentage tax on gross sales or receipts. It is filed quarterly using BIR Form 2551Q, separate from the income tax filing.
The percentage tax does not apply to:
- 8% flat rate filers. The 8% is in lieu of both the graduated income tax and the percentage tax.
- VAT-registered individuals. They pay VAT, not percentage tax.
For a graduated filer with annual gross of ₱1,000,000, the percentage tax is ₱30,000. The income tax is separate. Total BIR liability is the sum.
A Note on Corporate Tax
Corporations file BIR Form 1702Q, not 1701Q. The cumulative rule is the same. The rates are different.
- Regular Corporate Income Tax (RCIT): 25% of net taxable income. Reduced to 20% if net taxable income does not exceed ₱5,000,000 and total assets excluding land do not exceed ₱100,000,000.
- Minimum Corporate Income Tax (MCIT): 2% of gross income (gross sales less cost of goods sold and direct costs), starting from the fourth taxable year of operations.
- Applicable tax: whichever is higher between RCIT and MCIT.
Corporate tax is not covered further in this guide. The Ask W Calculator [Not AI] BIR Tax Estimator includes a corporate mode that computes both RCIT and MCIT and applies the higher amount.
Late Filing Penalties
Late filing or payment of quarterly income tax triggers three charges under NIRC Sections 248 and 249:
- 25% surcharge on the basic tax due.
- 12% per annum interest, computed from the due date to the date of payment.
- Compromise penalty, per the BIR schedule in RMO 7-2015.
Micro and small taxpayers, as classified under the EOPT Act, may qualify for a 50% reduction on the compromise penalty under RR 6-2024. The classification depends on gross sales and other criteria.
These penalties are not payable if the return is filed and paid on time. The due dates are:
- Q1: May 15
- Q2: August 15
- Q3: November 15
- Annual: April 15 of the following year
If a due date falls on a weekend or holiday, the deadline moves to the next working day.
How This Compares
As of October 1, 2026, the free tools available in the Philippines for business tax calculation fall into three groups:
- Payroll tools. These compute employee compensation, including withholding tax and government contributions. They do not handle business income tax, percentage tax, or VAT.
- Single-purpose business calculators. These handle business income tax or VAT, but not both on the same page. The user must combine the results manually.
- Paid or specialized tools. These handle specific taxes such as Expanded Withholding Tax or corporate income tax. They require registration, payment, or are built for a specific transactional purpose.
This tool handles individual and corporate income tax, percentage tax, and VAT on a single page with a unified cumulative quarterly view. It does not require registration, does not display ads, and does not store the figures entered.
What the Calculator Does Not Do
The Ask W Calculator [Not AI] - BIR Tax Estimator is an estimator. It does not file returns or generate BIR forms. It does not handle every case. Specifically, it does not handle:
- Mixed-income earners with both salary and business income.
- Special rates under PEZA, BOI, or CREATE MORE incentives.
- E-commerce withholding under RR 16-2023.
- Expanded withholding tax with variable rates.
- Local business tax from city or municipal permits.
- Precise penalty computation per the full BIR RMO schedule.
- MCIT carry-forward mechanics.
- Estates, trusts, partnerships, foreign corporations, or fiscal-year filers.
For anything outside the scope, consult a CPA or the BIR.
Why We Built It
Most free Philippine tax calculators are payroll tools. They compute salary withholding, SSS, PhilHealth, and Pag-IBIG. They do not compute business income tax, percentage tax, or VAT. The free tools that do handle business tax typically handle one piece at a time. Some handle income tax on one page and place VAT on a separate page. Some handle non-VAT freelancers but do not compute commercial VAT at all. The user ends up combining the results by hand.
This tool is different. It handles individual and corporate income tax, percentage tax, and VAT on one page, with a single set of inputs and one cumulative quarterly view. The calculations are deterministic. The formulas are the same arithmetic that would be used by hand.
This tool was built as an internal calculation engine for Wholesale Dito Store, the wholesale distribution arm of Clickerwayne Zelle Solutions Inc. It was published as a free public tool because the same problem affects every MSME in the country, not just this one. The internal version and the public version use the same formulas. The code and execution differ because the internal engine is built for corporate operations. No account is required, no ads are shown, and no data is collected from the calculation.
The tool is part of the Ask W [Not AI] family, alongside Ask W About The Price [Not AI], Ask W Direct [Not AI], and Ask W Calculator [Not AI] - Margin, Markup, and ROI. All are free to use and do not require registration.
For the reasoning behind the [Not AI] label and the zero-dependency stack, see Why We Built a Zero-Dependency Stack.
Frequently Asked Questions
Is quarterly income tax cumulative or per-quarter?
Cumulative. Each quarterly filing covers year-to-date income, then subtracts prior quarter payments. Q2 covers January to June. Q3 covers January to September. The amount payable is the difference between the cumulative tax due and the tax already paid.
Which is better, the 8% flat rate or graduated rates?
It depends on the expense ratio and the gross level. A filer with high gross and low expenses usually pays less under the 8% rate, because the 8% applies to gross minus ₱250,000 and does not require deductions. A filer with high substantiated expenses often pays less under graduated rates with itemized deductions. The comparison should be run on actual figures, not intuition.
Can I switch from 8% to graduated rates mid-year?
No. The election is generally irrevocable for the taxable year. The choice is made at the start of the year, on the first quarterly filing. A change can be made for the following year.
What happens if I exceed ₱3,000,000 in gross sales?
The 8% flat rate is disqualified. The taxpayer must switch to graduated rates for the entire year and register for VAT. Prior quarters must be recomputed under graduated rates, and the difference settled.
Do I still pay 3% percentage tax if I am on the 8% rate?
No. The 8% flat rate is in lieu of both graduated income tax and the 3% percentage tax. Graduated-rate filers who are non-VAT-registered pay the 3% separately using BIR Form 2551Q.
What is the ₱250,000 deduction?
Under the 8% flat rate, the first ₱250,000 of gross sales or receipts is not taxed. Tax is computed on the excess. The deduction applies once per year, not once per quarter.
What is the Optional Standard Deduction (OSD)?
OSD is a 40% deduction from gross sales for individuals who choose graduated rates. It does not require substantiation. It is an alternative to itemized deductions.
Does the calculator handle corporate tax?
Yes. The Ask W Calculator [Not AI] BIR Tax Estimator has a corporate mode that computes both the Regular Corporate Income Tax (RCIT) and the Minimum Corporate Income Tax (MCIT), and applies whichever is higher.
Is the calculator using AI?
No. The Ask W tools are deterministic calculators. Every result is arithmetic computed in the browser. There is no AI, no inference, and no interpretation.
Where is the calculator?
The Ask W Calculator [Not AI] BIR Tax Estimator is at wholesaledito.store/ask-w/calculator-bir-tax-estimator.
Summary
Quarterly income tax in the Philippines is cumulative. Each filing covers year-to-date income and subtracts prior payments. This is the mechanic most filers get wrong, and it is why a tool that computes it correctly matters.
Self-employed individuals have three options: 8% flat, graduated with OSD, or graduated with itemized deductions. The 8% is capped at ₱3,000,000 in gross sales and is in lieu of both graduated tax and the 3% percentage tax. Graduated filers who are non-VAT-registered pay the 3% separately.
The Ask W Calculator [Not AI] - BIR Tax Estimator computes all three options, the 3% percentage tax, the corporate RCIT and MCIT, the cumulative quarterly breakdown, and the penalties. It is free and does not require registration.
Outro
Published by The Sniffer, the strategic insights blog of Wholesale Dito Store. This article is provided as a public reference for self-employed individuals and business owners in the Philippines. Wholesale Dito Store is operated by Clickerwayne Zelle Solutions Inc, Forest Drive St., corner Country Drive, Country Homes, Biñan, Laguna 4024, Philippines. Questions can be sent to customercare@wholesaledito.store.
Tax rates and rules cited in this article are current as of October 1, 2026. Verify against the latest BIR issuances before filing.